
The Next Round in the Obesity Drug Market
Pfizer’s move to secure $1.5 billion in funding from the investment firm, Blackstone, to advance its late-stage GLP-1 candidate is heating up the obesity drug market. A look at the revenue leaders and contenders.
By Patricia Van Arnum, Editorial Director, DCAT, [email protected]
New products and players in the obesity drug market
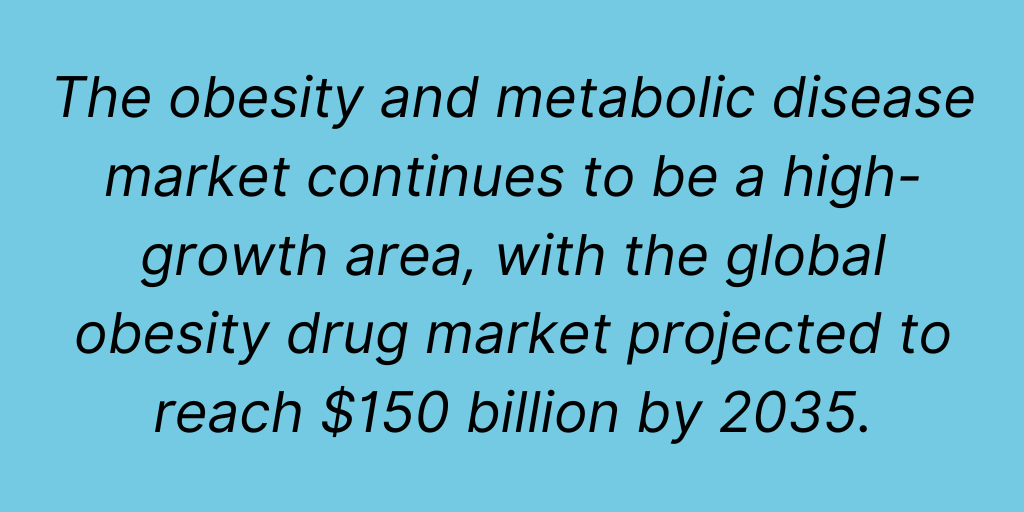
The obesity and metabolic disease market continues to be a high-growth area, with the global obesity drug market projected to reach $150 billion by 2035, according to a recent analysis by Insira (formerly the Life Sciences & Healthcare business of Clarivate), a business intelligence firm serving the bio/pharmaceutical industry. Glucagon-like peptide-1 (GLP-1) agonists, used to treat Type 2 diabetes and obesity, have been the industry’s success stories with Novo Nordisk riding a blockbuster wave with Ozempic/Wegovy (semaglutide), respectively for treating Type 2 diabetes and obesity, and Eli Lilly and Company also riding the wave with Mounjaro/Zepbound (tirzepatide), a dual-activating GIP (glucose-dependent insulinotropic polypeptide) and GLP-1 medication, respectively for treating Type 2 diabetes and obesity.
The obesity drug market is reaching a new phase, driven by new market entries and drug candidates. Chief among them is Lilly’s Foundayo (orforglipron), approved in April (April 2026) by the US Food and Drug Administration (FDA). It is an oral, non-peptide, small-molecule GLP-1 receptor agonist that can be taken without food or water restrictions at any time of the day. As such, it represents a breakthrough in convenience and accessibility compared with injectables. It is approved in the US for adults with obesity and in multiple countries for adults with obesity and Type 2 diabetes. In addition to Type 2 diabetes, it is being evaluated for treating obstructive sleep apnea, osteoarthritis knee pain, hypertension, peripheral artery disease and stress urinary incontinence. Lilly plans to submit Foundayo to FDA for moderate-to-severe obstructive sleep apnea in adults with obesity or overweight by the end of 2026, with other global submissions to follow.

Analysts project a blockbuster future for orforglipron with expected sales of $11.1 billion for obesity in G7 markets (Canada, France, Germany, Italy, Japan, the UK, and the US) in 2031, and $5.2 billion in expected sales for Type 2 diabetes in the G7 markets in 2031, according to the Insira analysis.
Lilly is also banking on retatrutide, in Phase III development, a single peptide with once-weekly subcutaneous administration with a triple mechanism of action (GLP-1, GIP and glucagon receptor agonist) to manage overweight and obesity and treat Type 2 diabetes. Analysts project $10 billion in expected sales of retatrutide for obesity in the G7 markets in 2031, and $20.1 billion in expected sales of retatrutide for Type 2 diabetes in the G7 markets in 2031, according to the Insira analysis. Near-term, analysts project that it will launch in 2028 in the EU (obesity), Japan (Type 2 diabetes), UK (obesity), and US (obesity and Type 2 diabetes) and in 2029, in the EU and UK for Type 2 diabetes. It is also being evaluated for treating osteoarthritis, low back pain, cardiovascular disease, and kidney disease in individuals with obesity as well as nonalcoholic fatty liver disease (NAFLD)/metabolic dysfunction-associated steatohepatitis (MASH).
In launching orforglipron, Lilly is competing with Novo and its oral obesity drug, oral semaglutide, the active ingredient in Novo’s injectable obesity drug, Wegovy, and injectable Type 2 diabetes drug, Ozempic. Oral semaglutide for treating obesity received FDA approval in late December 2025 and was launched in the US in January (January 2026). Novo already had an oral version of semaglutide, the active ingredient in Ozempic and Wegovy, on the market in Rybelsus, which was first approved in 2019, but that is indicated for treating Type 2 diabetes, not obesity.
In its obesity and diabetes franchise, Novo’s focus is two-fold: expand its position in the injectables market beyond semaglutide, the active ingredient in its blockbuster obesity/Type 2 diabetes drugs, Wegovy/Ozempic, and expand its position in the oral obesity drug market, which includes the already marketed oral form of Wegovy (semaglutide).
Novo says it is planning at least one major blockbuster obesity drug launch per year through 2030. This entails a goal of scaling capacity to be able to serve 10 times more people with obesity on oral GLP-1 medicines in the 2026–2030 time frame and overall serving more than 60 million patients globally by 2030. Key products include launches for CagriSema (cagrilintide and semaglutide) in 2027, cagrilintide (as a monotherapy) in 2028, zenagamtide in 2029, and other drugs with novel mechanisms of action in 2030 and beyond. CagriSema (cagrilintide and semaglutide) is a once-weekly injectable combination drug candidate for Type 2 diabetes and obesity, which pairs the amylin analog, cagrilintide, with the GLP-1 receptor agonist, semaglutide. Novo filed a new drug application with FDA in December 2025 for CagriSema for weight management. A decision is expected in the fourth quarter of 2026. Novo is also developing cagrilintide as a standalone treatment, which is Phase III development. Its other key drug candidate, zenagamtide, also known as amycretin, is an unimolecular peptide agonist of GLP-1 and an amylin receptor under clinical trial development with separate programs to investigate treatment for adults with Type 2 diabetes and for adults with overweight or obesity. Zenagamtide is also under investigation for both oral and subcutaneous administration.
Last year (2025), Novo Nordisk had sought to further position itself in the obesity drug market with a bid to acquire Metsera, a New York-based clinical-stage bio/pharmaceutical company focused on obesity and cardiometabolic diseases, eventually losing a bidding war with Pfizer, which acquired Metsera last November (November 2025). Metsera’s portfolio included both oral and injectable incretin, non-incretin, and combination therapy candidates.
Pfizer is advancing the late-stage development of one of those assets gained from its acquisition of Metsera, berobenatide, an investigational monthly GLP-1 receptor agonist peptide in Phase III development for chronic weight management and obesity-related conditions. This week (November 11, 2026), Pfizer announced that it had formed a strategic co-funding agreement with Blackstone Life Sciences under which funds managed by Blackstone will pay up to a total of $1.5 billion of development costs through 2028 for berobenatide. In exchange for the funding, Blackstone will be eligible to receive milestone-based payments, subject to US regulatory approval of monthly dosing of injectable berobenatide monotherapy for chronic weight management and the achievement of certain commercial sales milestones.
Pfizer says it plans to advance 20+ trials for obesity and related comorbidities in 2026. This includes 10 ongoing and planned Phase III trials for berobenatide for chronic weight management and obesity-related comorbidities, including knee osteoarthritis and obstructive sleep apnea.
Roche is advancing an oral GLP-1 receptor agonist for obesity, tifeglipron (CT-996), which it gained through its 2024 acquisition of Carmot Therapeutics, a Berkeley, California-based bio/pharmaceutical company, in a deal worth up to $3.1 billion ($2.7 billion at closing plus $400 million in potential milestone payments). The acquisition provided Roche with three clinical-stage assets with potential in treating obesity and diabetes: as previously mentioned, tifeglipron (CT-996), a once-daily oral small-molecule GLP-1 receptor agonist for treating obesity in patients with and without Type 2 diabetes, as well as two injectable clinical drug candidates: enicepatide (CT-388), a once-weekly subcutaneous injectable for treating obesity in patients with and without Type 2 diabetes, and CT-868, a once-daily subcutaneous injectable, for treating Type 1 diabetes patients with overweight or obesity.